diversification

Trends May Not Persist: What’s on the other side of the peak? 

The most pertinent warning for investors in the AI age might be, “Trends may not persist.”

We humans tend to believe that current conditions or trends will continue. In recessions, we can scarcely imagine how the economy will ever recover. And when the markets get into bubble territory, it seems the good times will never end.

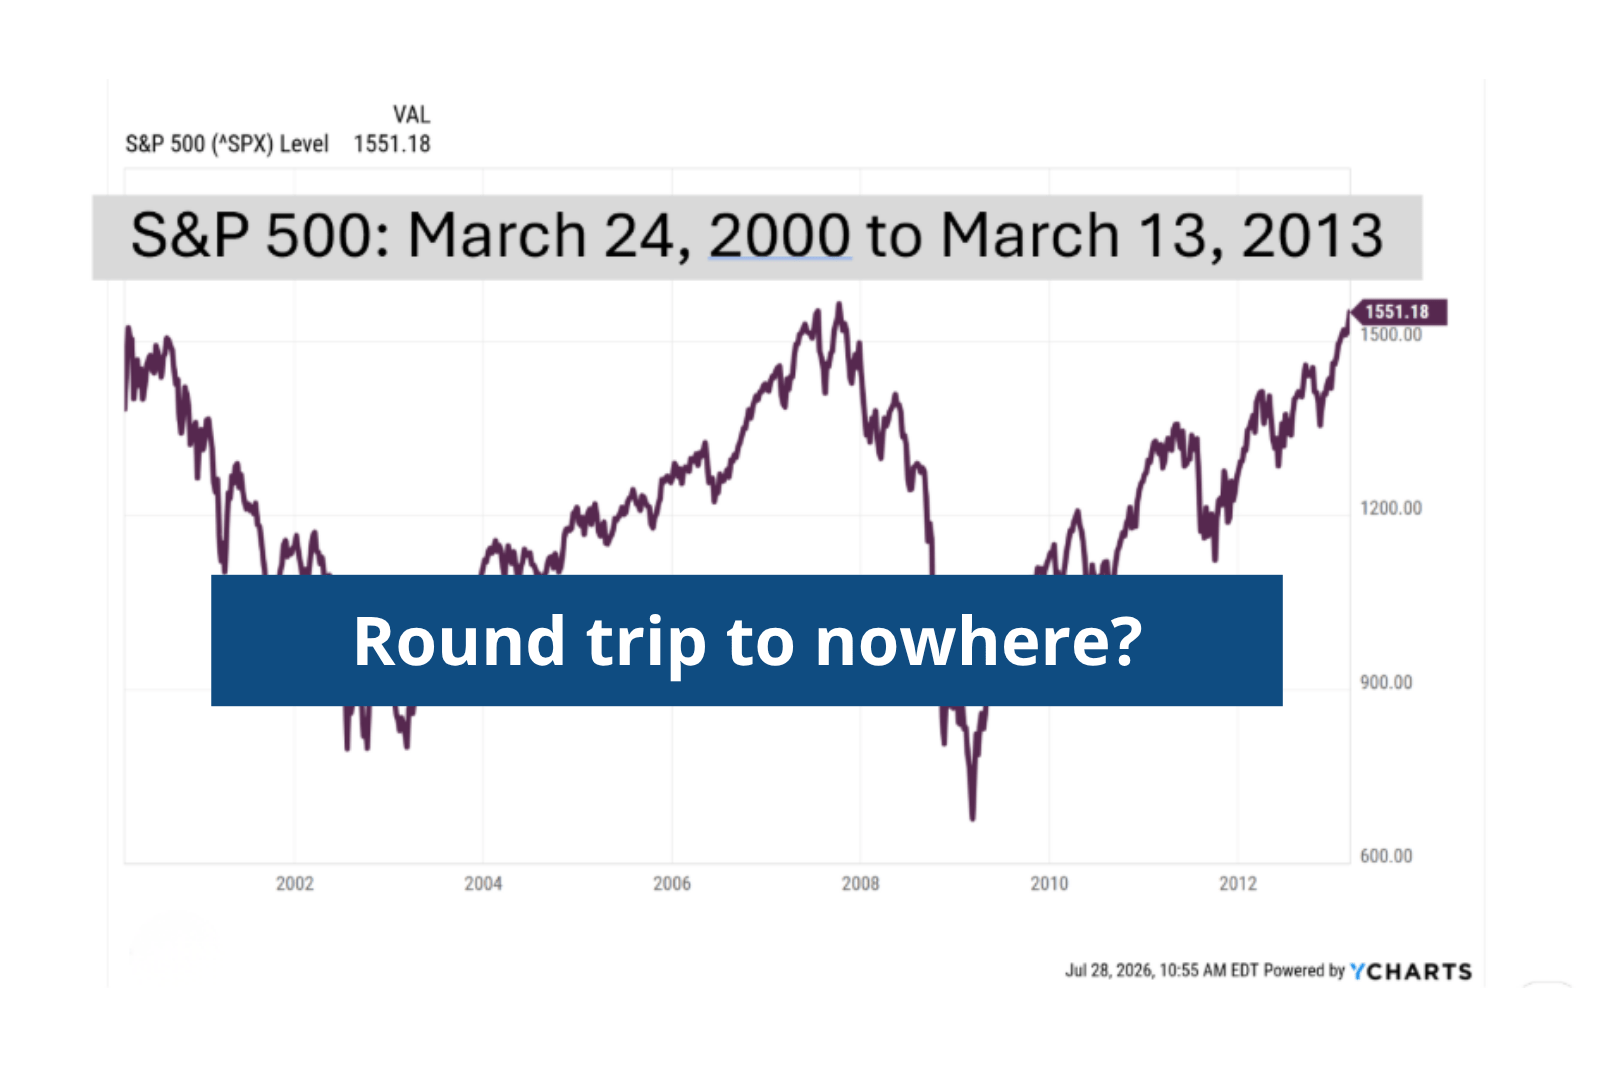
That was certainly the case in March of 2000, at the peak of the Internet Boom. The S&P 500 had basically tripled in five years and became dominated by large technology companies.

“The internet was going to change everything,” they said—and that story came true.

But valuations had gotten so excessive, the S&P 500 suffered a Lost Decade when the trend changed: it took nearly 13 years on a round trip to nowhere. Fortunately, the S&P 500, composed of the stocks of large U.S. companies, is not the only game in town. Small and mid-sized companies, value stocks, international companies, and other opportunities held up much better, sometimes even making gains during the flat spell.

This history lesson is key to why we are not chasing the index here at 228 Main, especially right now. Looking for bargains, avoiding stampedes—these fundamental principles help us avoid the extremes. Most of us don’t have thirteen years to wait for a market recovery, so it makes sense to strive to be in those parts of the investment universe that are more reasonably priced, now.

As in 2000, the index has become dominated by large technology companies, this time as part of the AI boom. We are paying attention to our principles, mindful that these trends may not persist.

We pay, temporarily, in performance. Our approach has us lagging the S&P 500 recently; we’re not going up by as much, but our efforts now are made in an attempt to potentially go down by less when the bust comes. No guarantees. But we’re turning to history as a guide.

Clients, now as ever, reach out any time with your questions. We’re here to help.


Neither the past performance of the S&P, nor the described methodology, is a guarantee of future returns.

Content in this material is for general information only and not intended to provide specific advice or recommendations for any individual. All indices are unmanaged and may not be invested into directly.

All investing involves risk including loss of principal. No strategy assures success or protects against loss.


Want content like this in your inbox each week? Leave your email here.

Play the audio version of this post below:

Trends May Not Persist: What’s on the other side of the peak? – 228Main.com Presents: The Best of Leibman Financial Services

The text of this episode is available at ⁠⁠⁠⁠⁠228Main.com⁠⁠⁠⁠⁠.

Choose Your Ingredients 

by Mark Leibman, Advisor

I learned how to make soup back in the last chapter. Now a variety of soups are a staple of my diet. 

Crafting a new soup recipe recently, I started with a chicken, six herbs and spices, and seven kinds of vegetables. I used some olive oil and a splash of red wine vinegar. It may be served with a mix of seven kinds of beans, and rice, of course (you know how I feel about rice and beans!). 

It came out really good!—according to a biased observer that I recently married.  

Contemplating the choices made in the creation of the soup, I thought about how we build portfolios here at 228 Main.  

From many alternatives, we select what we want to own and determine the proportions of each. Another school of thought holds that portfolios should consist of some of everything—500 stocks go into the S&P 500 index, for example, so portfolios get to hold a little of each. 

That led me to wonder, What would Index Soup look like? 

  • 150 herbs and spices? 
  • 50 kinds of vegetables? 
  • Beef, pork, chicken, fish, and eight more kinds of animal protein? 

And it might even be served with 25 kinds of beans, and 10 varieties of rice! 

That would have to taste like a little bit of everything, and not much of anything, wouldn’t it? 

Just as different recipes can reflect a wide variety of tastes and textures and smells, and we humans have an appetite for different things at different times, our portfolios evolve and change as conditions unfold. 

By looking for the best bargains, by avoiding stampedes in the market, by planning to own the orchard for the fruit crop (thinking long-term), our collection of opportunities has diverged from the most popular kind of Index Soup, the S&P 500.  

Creating our own recipe helps avoid another possible pitfall of Index Soup—not that it can get too bland in its attempt to average everything, but that it can get too heavy-handed in spicy times. 

Recently, slightly more than half of our long-term portfolios are invested in small- and mid-size companies. We’re diversified around the world, although about two-thirds of value is still invested in the U.S. While AI-related stocks have captured the public imagination, we’re focused a little more on value-style stocks than the mega-size growth companies, which we believe may be over-valued at present. No guarantees, but we’re trying to be intentional with our flavors. 

Meanwhile, Index Soup focuses on large U.S. companies, with an emphasis on growth. Technology is nearly 37% of the mix in that soup, and the top seven holdings are mega-size tech companies.  

We know that the flavor can get “too strong” at times: back in the year 2000, the S&P 500 index, and technology stocks generally, left a bad taste in the mouths of many investors the last time valuations approached extreme levels.  

We can’t know the future, but we are hopeful our recipe is going to “taste” a lot better in the months and years ahead. No guarantees—past performance is not an indicator of future results. 

But we don’t have to be the best chefs in the world. We’re just trying to find a blend that works for us. 

Want content like this in your inbox each week? Leave your email here.


Investing involves risk including the loss of principal. There is no assurance that the views or strategies discussed are suitable for all investors or will yield positive outcomes. 

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual. There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk. 

The S&P 500 is an unmanaged index which cannot be invested into directly. Past performance is no guarantee of future results.  


Play the audio version of this post below:

The text of this episode is available at ⁠⁠www.228Main.com⁠⁠.

Portfolio Themes: Fall 2022 Edition

graphic shows a photo of a basket of apples and the words "Fall Themes"

Investment research is an ongoing process here at 228 Main. Real-world developments are always intersecting with the changing prices of shares; the mosaic looks a little different each day. In our weekly meetings, we review news about companies we own, trade our insights, and talk about emerging bargains or trends. 

We think about what we own—and why. 

We sometimes find bargains in a particular industry or sector. Other times we study trends and try to sort out who will benefit in the years and decades ahead. Looking over the whole Buy List, patterns emerge. 

The single biggest theme often surfaces as a result of our search for quality companies at fair prices. Dominant, sector-leading firms—the blue chips—run the gamut from big green farm machines and home improvement chains to the largest retail health company and the biggest player in a highly fragmented industry (a consolidation play). This is where you’ll find Warren Buffett’s company, too. 

Emerging growth companies may benefit from increasing connectivity, innovation, and automation. Paired with the large technology companies who make the devices, systems, software, and chips we depend on every day, we have solid exposure to what seem to be likely growth areas in our economy. 

Natural resources have been a focus for years, and we continue to refine our thinking as the energy revolution unfolds. Copper and other industrial metals may have favorable supply-and-demand outlooks for years and decades to come. The fossil fuel industry persists, even as alternative energy becomes an increasing fraction of our total energy needs. 

The evolution of the automobile continues to intrigue us. We have exposure to this theme via big tech companies and copper producers, but also via ownership of automakers old and new, plus a supplier of sophisticated components that support the evolution of mobility. 

International diversification in Europe and India makes sense to us, and a few plain old bargains (in our opinion) round out our list. Among the shifting landscape in Europe and one of the world’s largest populations in India, we recognize some opportunities for exposure. 

Clients, we share a long time horizon; we stay focused on major trends. This approach provides some continuity in our thinking across the years, even while we work hard to understand the day-to-day factors affecting our holdings. It’s a thrilling challenge, and we’re always happy to share our thinking with you! 

Please call or email us when you want to discuss how this relates to your plans and planning. 


The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual. 

Investing includes risks, including fluctuating prices and loss of principal. 


Want content like this in your inbox each week? Leave your email here.

Play the audio version of this post below:

This text is available at https://www.228Main.com/.

What Do I Do with All These Retirement Accounts? Some IRA Strategies and Tactics

photo shows a group of pink piggy banks on a blue surface

There is no law against having more than one retirement account. But it is possible to take this too far—and get yourself a headache down the road. Instead, we’d like to suggest some IRA strategies and tactics that may help.

One person we know is dealing with Required Minimum Distributions (or RMDs) on four accounts in different institutions. Another, recently widowed, is faced with seven sets of IRA beneficiary claim forms in order to consolidate things. And many others have to struggle to understand the overall situation because information about different accounts comes in different forms at different times.

We help by consolidating smaller accounts in various locations into a larger, central account where total values are reported each month and are available online any time. RMDs, beneficiary claims, and other administrative tasks only need to be handled one time instead of many times.

There may be an edge, too, in having an intentional investment strategy that guides all tactical decisions, based on sound principles. In our diversified portfolios, we are able to select the precise source of funds when needed from among dozens of holdings. And we know which options are at the top of our list whenever new money becomes available to invest.

We believe this is a superior approach than just putting money in or taking it out of “the market,” although we can offer no guarantees.

And none of this is to mention that the quality of our advice and perspective might be improved when we’re able to understand all the pieces of the puzzle.

At the end of the day, organizing our abundance is a pretty wonderful problem to have. Wealth seems to be more useful when we understand its meaning, what it can do for us in our real lives. So if you would like to visit about this or anything else, please email us or call.


Want content like this in your inbox each week? Leave your email here.

Play the audio version of this post below:

What Do I Do With All These Retirement Accounts? Some IRA Strategies and Tactics – 228Main.com Presents: The Best of Leibman Financial Services

This text is available at https://www.228Main.com/.

A Structural Reminder

pyramid

The ability to adapt to changing conditions is what sets those who thrive apart from those who merely survive.

Our portfolio theory evolves over time as economic and market conditions unfold. The problem with the textbook approach in a changing world is that a textbook, once printed, never changes. Looking at the world as it is and doing our own thinking, we see things in a new way.

Some time ago, we concluded that counterproductive monetary policies have distorted pricing for bonds and other income-producing investments. By crushing interest rates and yields to very low levels, the old investment textbook had been made obsolete.

Therefore the classic advice about the proper balance between stocks and bonds brings new and perhaps unrecognized risks, with corresponding pockets of opportunity elsewhere. Yet the classic advice met a need which still exists: how to accommodate varying needs for liquidity and tolerance of volatility.

Our adaptation to this new world is the portfolio structure you see above. Our classic research-driven portfolio methods live in the Long Term Core. We believe our fundamental principles are timeless, and make sense in all conditions.

But people need the use of their money to live their lives and do what they need to do. So a cash layer may be needed, tailored to individual circumstances.

The layer between is ballast. This refers to holdings that might be expected to fall and rise more slowly than the overall stock market. Ballast serves two purposes. It dampens volatility of the overall portfolio, thereby making it easier to live with. Ballast may serve as a source of funds for buying when the market seems to be low.

The client with higher cash needs or who desires lower volatility may use the same long term core as the one who wants maximum potential returns. One may want a ‘cash-ballast-long term core’ allocation of 10%-25%-65% and the next one 4%-0%-96%. It’s a free country, you can have it your way.

It may be time to review the structure of your portfolio. Clients, if you would like to talk about this or anything else, please email us or call us.


Content in this material is for general information only and not intended to provide specific advice or recommendations for any individual.

All investing involves risk including loss of principal. No strategy assures success or protects against loss.

All or Nothing

© Can Stock Photo / agencyby

We keep hearing reasons why financial advisors should have 100% of every client’s invested assets, instead of some fraction. This theory is popular with… financial advisors.

You might guess we have a contrarian opinion on this subject, like most subjects. Our theory is that we end up with all the business we deserve. Since you who own the money are the judge of that, we are relieved of the burden of worrying about it. We don’t want any money in our shop that doesn’t want to be here, after all.

There are sound reasons to consolidate assets in one place – including lower costs through volume discounts. But some may prefer not to do that, for whatever reason.

Our investment approach is different than most. Rather than use the standard pie chart approach of owning a little bit of everything, or outsourcing investment management to some third party somewhere, we do hands-on research and our own thinking, using individual securities as appropriate. So our work is a useful diversification, something different, from run-of-the-mill conventional portfolio management using investment products instead of stocks and bonds.

When somebody wants to allocate a fraction of their wealth to our care, it is fine by us. We already know how much business we will ultimately end up with: all that we deserve.

It turns out that remembering whose money it is not only respects the people who engage with us, but also reduces our stress.

Clients, if you would like to talk about this or anything else, please email us or call.


Content in this material is for general information only and not intended to provide specific advice or recommendations for any individual. All performance referenced is historical and is no guarantee of future results. All indices are unmanaged and may not be invested into directly.

All investing involves risk including loss of principal. No strategy assures success or protects against loss. There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk.

The Trouble with Zig and Zag Theory

© Can Stock Photo / chokniti

The idea behind massive diversification, owing a bit of everything, is that some things zig when others zag, keeping the whole bucket steadier. Great theory.

The problem is that things do not zig and zag ALL the time. When the big downturn comes, they all go down together. Oh, some things do not go down – but those things also tend to never go up, either.

The mathematical basis for massive diversification is Modern Portfolio Theory. It depends on different types of assets behaving more or less independently of one another – zigging and zagging. The lack of correlation is what drives the hypothetical usefulness of the theory.

In the big downturns, however, the correlations may converge. In plain language, in times of market stress, even independent investments may act as though they are related. The theory may not work due to systematic risks.

This is a real problem, because it is a theory that sometimes has the potential to drive investors to diversify into sectors and asset classes which may hold unknown risks, in the interest of avoiding market volatility.

This only makes sense if one defines volatility as risk, something to always be minimized and avoided. We think it makes more sense to understand volatility as an integral and necessary part of long term investing, a feature to be tolerated (or embraced) as the price of pursuing market returns over the long haul.

Investing in fluctuating markets with confidence requires us to know where our needed cash will come from – only long term money should be invested for the long term.

Clients, if you would like to talk about this or anything else, please email us or call.


The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Would You Take Every Drug on the Shelf?

canstockphoto16219846

We have written quite a bit about the conventional investing wisdom recently. This essay puts the focus on what we do here at 228 Main.

One of our principles is to find the best bargains. We cannot be sure where they are, but we will still try to find them. We look for seemingly healthy investments at historically low-seeming valuations.

We recognize this means buying investments which are unpopular. This is fine with us. In fact, we rely on it. One of our core principles is to avoid stampedes. The more of something everyone else is buying, the more expensive it is going to get.

A natural consequence of our approach is that our portfolio construction may not be as diversified as conventional wisdom dictates. But we are not interested in trying to own everything. We want to own the bargains.

We may not always be able to pick them. We may miss out on some high flyers because we thought they were too expensive to buy. Sometimes a “bargain” turns out not to be one. Generally, though, we believe that our odds are better if we at least try to find the bargains.

An alternative to our way is like going to a doctor who prescribes every drug he can think of in case one of them works. “Chances are some of them will make things better and some of them will make things worse, but in theory one of them should cure you.” Wouldn’t you run out the door?

There are many unknowns in both medicine and investing. A doctor may have to try several courses of treatment before finding one that works. Similarly, we frequently implement several promising tactics at the same time. Some don’t work out and need to be replaced.

We think it is reckless, however, to simply give up trying to find successful investments in favor of simply grabbing a little bit of everything. Yet that seems to be a popular, if lazy, strategy with some investment professionals.

Clients, please call or email us if you want to discuss how our investment ideas apply to your situation.


The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Investing involves risk, including possible loss of principal.

There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk.

No strategy assures success or protects against loss.

Two Robbers Lurk in the Shortcut

canstockphoto38874611

The investment methodology promoted by most financial professionals has a costly shortcut at its core. A mathematical trick is used in place of common sense, one that simply equates volatility with risk.

The shortcut enables people to pretend that statistical models can predict the future risk in any portfolio. The model always works perfectly, until it doesn’t. Three Nobel Prize-winners using these kinds of models blew up a hedge fund with billions of dollars in 1998. The failure of Long Term Capital Management caused an international crisis.

Warren Buffett wrote a wonderful analysis of this issue in his 2014 letter to shareholders. He explained that stock prices will always be more volatile than cash holdings in the short term. But he believes that fixed-dollar investments are far riskier than widely diversified stock portfolios over the long term.

One of the robbers that lurks in the shortcut is inflation. A dollar today will only buy 98 cents worth of goods next year, and 96 cents the year after that. Buffett wrote in 2014 that the dollar had lost 87% of its purchasing power over the previous 50 years. So over the long haul, the stable fixed investment becomes quite risky in terms of the potential to melt your wealth away.

While the high risk in currency-denominated investments did its damage, the same 50 year period saw the S&P 500 advance by 11,196%. Another of the robbers lurking in the shortcut is missed opportunity for long term gains.

Fortunately, you can spot the shortcut fairly easily. Every one of the following situations involves costly confusion about volatility and risk:

1. When every market sector supposedly needs to be owned for proper diversification. Our view: Some sectors are overpriced and should not be owned—tech stocks in 2000, real estate in 2007, commodities in 2011, and so forth.

2. When the presence of declining elements in a portfolio is held as proof of proper investment process—the idea that some things always zig when others zag, and keep the whole bucket more stable. Our view: When a crisis hits, many things decline across the board.

3. When a short-term decline is spoken of as ‘a loss.’ Our view: This is a costly misperception, born of a short-sighted approach.

4. When the future returns of a portfolio are described as a range that will be accurate 95% of the time—this is a hallmark of the statistical model. Our view: The model knows the past. The future will be different than the past. The wheels will come off the model when these differences emerge.

No one knows what the future holds. Our approach is to avoid stampedes, seek the best bargains, and strive to own the orchard for the fruit crop. These principles help us pick our spots, so to speak, rather than think we need to own a little bit of everything no matter what. The principles are no guarantee against loss.

The key advantage in our method, we believe, is avoiding the robbers who lurk in the shortcut. No systematic wealth melting from unneeded stagnant fixed investments, no missed opportunities for long term gains. We have no guarantees that our approach will be superior.

Clients, you know that one thing is required of you in order to have a chance to be successful with our methods. The understanding that volatility is NOT risk is key. Please call us or email if you would like to discuss this at greater length.


The Standard & Poor’s 500 Index is a capitalization weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries.

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual. All performance referenced is historical and is no guarantee of future results. All indices are unmanaged and may not be invested into directly.

The economic forecasts set forth in this material may not develop as predicted and there can be no guarantee that strategies promoted will be successful.

Stock investing involves risk including loss of principal.

Bonds are subject to market and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise and bonds are subject to availability and change in price.

The economic forecasts set forth in this material may not develop as predicted and there can be no guarantee that strategies promoted will be successful.

There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk.

The State of Our Union

© Can Stock Photo / Niyazz

Our union? Yes, you and we are partners in a unique enterprise. As a client, you share our confidence about the long term. Many of you are willing to live with volatility in the short term to get where you want to go. And many of you don’t join stampedes or sell out in panic. This investment behavior puts you in a select group. It is a vital ingredient in the beginning of your success—and ours.

The 21st anniversary of the decision to embark on our ultimate business venture is a natural time to take stock. Where are we now? Where are we going? We’ll assess this in terms of our three key activities.

Communications.

We love to talk—you know this. About two years ago, we began to figure out how to talk to all of you, every day if you would like. The new media has two aspects. Real time commentary and news shows up in the social media venues like Facebook and Twitter. A permanent library of all of our philosophy and strategies and methods can be found 24/7 at 228Main.com.

Paradoxically, the success of our new media has given us more time to talk one on one, by telephone or email or in person. So now we spend more time doing what we love, connecting with you directly. We expect to continue to build both our archives and our skill at real time interaction.

Investment Research.

To a surprising extent, our research capabilities are tied to new media activity. We interact with great minds in economics and market strategy, trading ideas and insights and finding topics we wish to investigate more deeply.

The one-to-one communications with you also contain a research element. We gain perspective on global markets by talking to executives who have traveled the world on business. We have a better understanding of specific industries and companies because we talk to people who are in those businesses. Every one of you is a consumer, and we talk to you about companies and products you deal with every day.

Our conventional sources have never been better, either. LPL Financial continues to build out our back office research staff by adding and developing talent. Bottom line: we are connected to ever-richer sources of ideas and trends as well as the specific data we need to do our work.

Portfolio Management.

Over the past eighteen months we have worked on improving our capability to act more quickly on fleeting opportunities. You saw the results. Our portfolio review process is more robust than it ever has been.

We also have tweaked our strategy. Now, client portfolios see more activity but in smaller pieces. Instead of looking for opportunities where we can invest 5% of a portfolio balance, we will take action if 1 or 2 or 3% position sizes are appropriate. With more holdings comes greater diversification. Theoretically, this may give us a smoother ride to our goals.

The markets are like a thousand piece mosaic whose tiles are constantly changing. So we cannot tell you what changes are coming in the future—only that we will always be trying to figure out how to grow your buckets more effectively.

So the state of our union is grand. We have focused on our systems and processes so we can take care of business no matter what happens in our lives or the economy and markets. We offer no guarantees about the future, except for our intent to get better as we go along. Thank you all for your part in our unique partnership. Clients, if you’d like to talk at greater length about these things or anything else, please email or call.


The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk.