The Joy of Free Wins

canstockphoto25929752

People or companies may confer benefits on third parties without cost, as a side effect or byproduct of their actions. Planting a tree improves the neighborhood and provides shade to a neighbor. Keeping bees results in the pollination of nearby crops. Providing first-aid training to workers may save lives outside of work. A video or blog post created for clients might contain an idea that helps people who are not clients.

These are examples of what economists call positive externalities. These things are all good. They make the world a better place.

I believe the concept applies in our interactions with others, as well. Have you ever had your day brightened by the laughter of a group of passersby? Watched someone hold a door for someone with an armload of packages? Overheard a “thank you” being given for an otherwise thankless task?

All of these things are benefits that they produced for free and you enjoyed at no extra cost. They are positive externalities, on the small scale of daily life.

Having a tree planted improves our home as well as the neighborhood, but generating positive externalities can also help us beyond business transactions. Friends and family members respond to the empathy, kindness, and thoughtfulness embedded in any of those little actions we can take. If employed, those in our network are likely to sense the intangibles we add to the workplace environment. Our teammates across the community likely enjoy our interactions more.

Generating positive externalities is not charity. There are no costs involved, only benefits for giver, recipient, and neighbors and passersby. Win-win-win.

The general concept has been around for a long time, and is often expressed more simply. Be kind. Fill up the buckets of others. Do unto others.

Clients, if you would like to talk about this or anything else, please email us or call.


Want content like this in your inbox each week? Leave your email here.

Play the audio version of this post below:

The text of this episode is available at http://www.228main.com.

Thirty Years In! A Note from the Founder 

by Mark Leibman, Advisor

Thirty years ago this month, I sat down at the kitchen table and went to work—Day One—in Leibman Financial Services. I’d had the idea for more than a decade that I could assemble a group of clients, who, if I took care of them, they would take care of me. At age 40, it was time to test the theory. 

The stakes were high. My life in financial services had been transactional up to that point. I knew if I did not change, I might wake up at sixty years old, needing to run up and down the highway to make a deal to pay for groceries. A sales mindset was not sustainable. 

Getting serious about managing portfolios for people meant that my business objective could be simplified into this: grow the clients’ buckets

It was hard, starting from scratch. We struggled and juggled for years. But business began to compound. Investment returns grew client balances, which grew revenue. Four years in, the quaint office building at 228 Main in beautiful downtown Louisville came available. I could neither afford it, nor afford to pass it up, so you know what I did! 

Business doubled. And doubled. And doubled. And doubled. It turns out people like it when the focus is on growing their buckets. 

The one-man band became a team of eight, eventually. I’m well down the path of working to age 92, with the enterprise around me that makes it possible. (Hey, Dylan is touring at age 85! I’m only 70.)  

In this 30th anniversary month, I’m thinking of you, clients, grateful for your part in this glorious journey. Here’s to the next 30.  


All investing involves risk including loss of principal. No strategy assures success or protects against loss. Past performance is no guarantee of future results. 


Play the audio version of this post below:

Thirty Years In! A Note from the Founder 228Main.com Presents: The Best of Leibman Financial Services

The text of this episode is available at http://www.228main.com.

Dazzled by Diamonds?


No matter how beautiful, some flowers still have thorns. And no matter how flashy, some salespeople will have them too. Remember that not every person you meet will have your best interest at heart. Don’t let any peddlers dazzle you with diamonds! It never hurts to ask for a second opinion.

Want content like this in your inbox each week? Leave your email here.

Saving Summer?

photo shows a shiny red push lawnmower sitting in green grass in front of a brown picket fence

In the United States, as in most places in the world, we are governed by the Gregorian calendar. But as we flipped the page and entered the “-ber” months, many of us are facing once again the power of the all-important academic calendar. 

Children, grandchildren, and neighbors are back to school. Summer is over for most of the country, and it’s got us reflecting. Without school, summer for many families can include more sleepovers or late nights and long chats on the porch. It could mean hours at the city pool or a big vacation. 

For some of us, summers have also meant more leisure and more work. 

It’s possible that you earned your very first dollar—and then some, hopefully—one summer long ago. Teens are more likely to be employed during June, July, and August than any other time of year. And it makes sense: teens are more likely to have the time and opportunity then, as jobs like lawnmowing, babysitting, and lifeguarding peak each summer. 

Clients, if anyone in your household age 18 or under was out making money this summer, consider talking with them about the “Swiss Army Knife of finance”: the Roth IRA

As long as someone has earned income (and doesn’t make more than the cap), they can contribute to a Roth IRA (up to the maximum amount).

Say your child or grandchild earns $3,000 in the summer: they could contribute up to $3,000 to a Roth. Of course, they may not want to forfeit all their earnings, but if they’re able to, this may be a prime opportunity to impart the value of saving. If you’re feeling nice, you could “gift” them the $3,000 to replace what they saved.

Roth contributions are taxable now and enjoy tax-free future gains. Beyond the magic of compounding, starting a Roth account early has other benefits: 

  • At any time, you may withdraw contributions without facing a penalty or taxation. 
  • Beginning five years after the Roth was opened and funded, account holders can take out up to $10,000 (earnings and contributions) to fund the purchase of their first home, tax- and penalty-free.  
  • Beginning five years after the Roth was opened and funded, account holders can use it to pay for qualified college expenses, penalty-free (earnings will be taxed as regular income). 

As children near college age, investors may have questions: the government does not include retirement accounts as assets in the calculation for student aid, so this type of savings vehicle should not impact the availability of federal financial aid. 

Withdrawals would be counted in the calculation, but be aware: the FAFSA uses a “prior-prior year” income picture to avoid having to base their decisions on estimations. So, for example, even withdrawals made in a 4-year graduate’s junior year shouldn’t affect their aid eligibility. 

The process of getting something like this set up isn’t terribly complicated. It is not necessary for the working person have a W-2, though we do recommend keeping records (think: basic invoices or even simple receipts from the neighbors for those lawnmowing or babysitting services). 

Clients, could this be a way to help your children or grandchildren preserve a piece of summer? Call or write, anytime.


A Roth IRA offers tax deferral on any earnings in the account. Qualified withdrawals of earnings from the account are tax-free. Withdrawals of earnings prior to age 59 ½ or prior to the account being opened for 5 years, whichever is later, may result in a 10% IRS penalty tax. Limitations and restrictions may apply. 

This information is not intended to be a substitute for specific individualized tax advice. We suggest that you discuss your specific tax issues with a qualified tax advisor. 


Want content like this in your inbox each week? Leave your email here.

Play the audio version of this post below:

The text of this episode is available at ⁠⁠⁠⁠228Main.com⁠⁠⁠⁠.

What’s The Best Time To Start?

“Well begun is half done,” the proverb says. And we tend to agree. Since it’s your journey, we don’t like to sweat the particulars: it’s never too early to start, but it’s also never too late.


Want content like this in your inbox each week? Leave your email here.

Trends May Not Persist: What’s on the other side of the peak? 

The most pertinent warning for investors in the AI age might be, “Trends may not persist.”

We humans tend to believe that current conditions or trends will continue. In recessions, we can scarcely imagine how the economy will ever recover. And when the markets get into bubble territory, it seems the good times will never end.

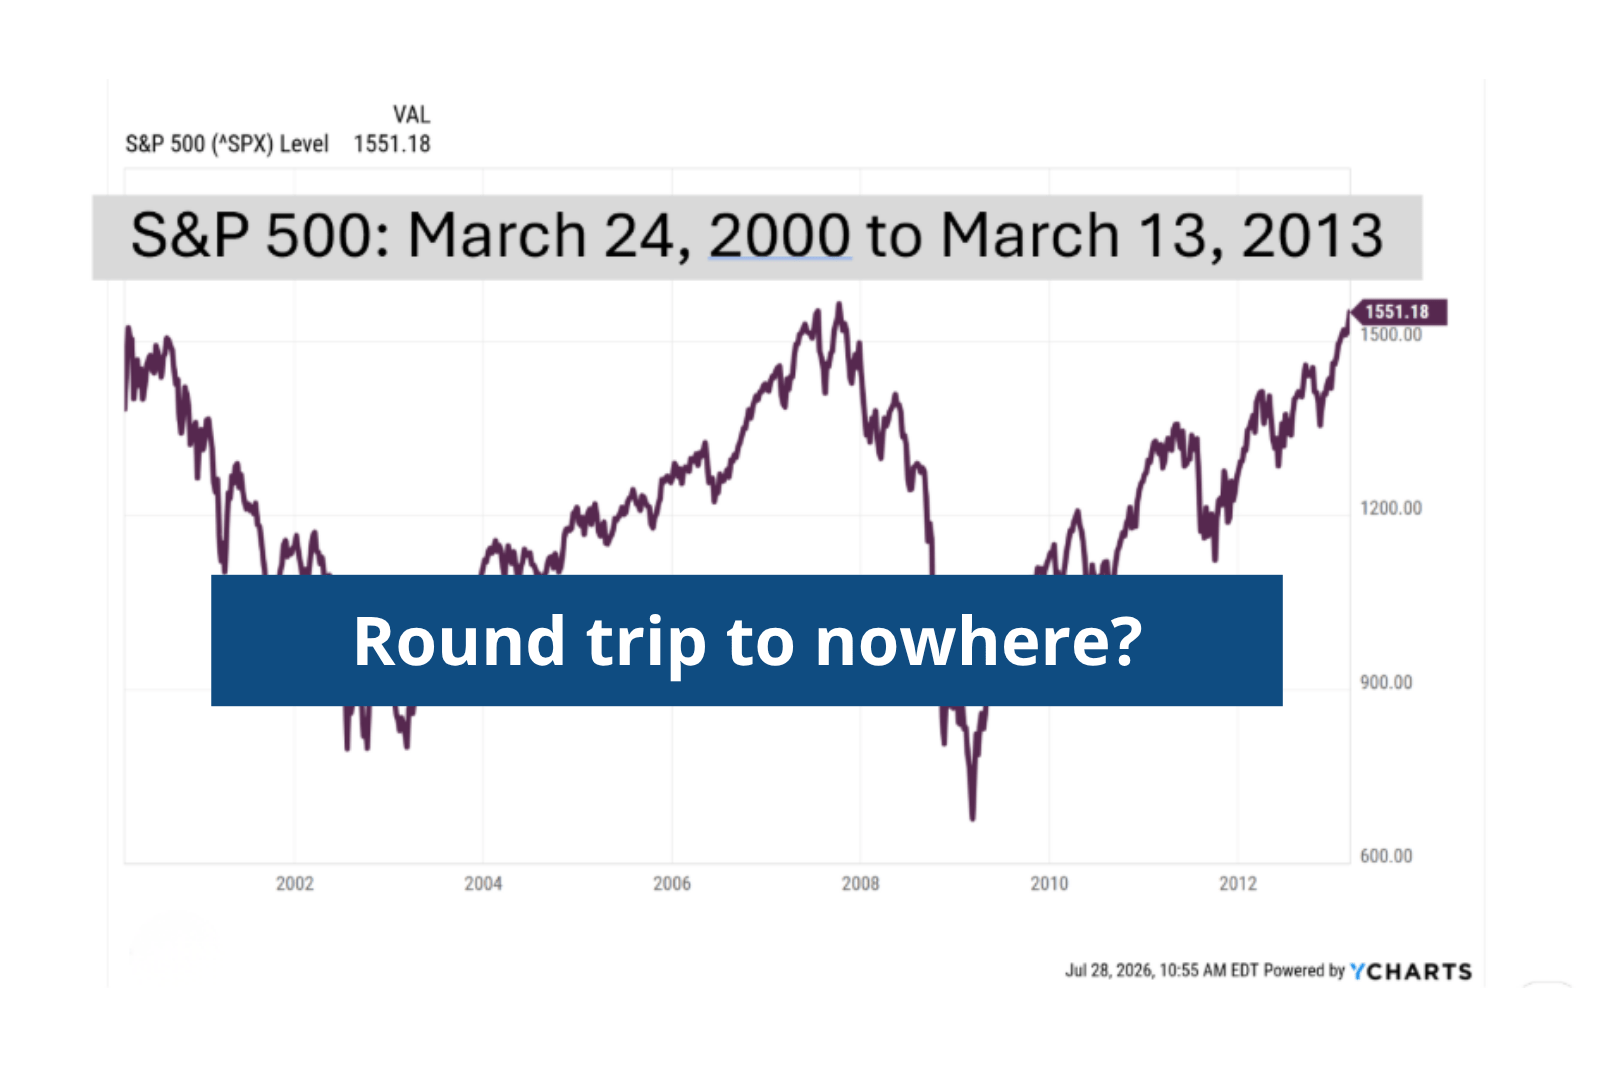
That was certainly the case in March of 2000, at the peak of the Internet Boom. The S&P 500 had basically tripled in five years and became dominated by large technology companies.

“The internet was going to change everything,” they said—and that story came true.

But valuations had gotten so excessive, the S&P 500 suffered a Lost Decade when the trend changed: it took nearly 13 years on a round trip to nowhere. Fortunately, the S&P 500, composed of the stocks of large U.S. companies, is not the only game in town. Small and mid-sized companies, value stocks, international companies, and other opportunities held up much better, sometimes even making gains during the flat spell.

This history lesson is key to why we are not chasing the index here at 228 Main, especially right now. Looking for bargains, avoiding stampedes—these fundamental principles help us avoid the extremes. Most of us don’t have thirteen years to wait for a market recovery, so it makes sense to strive to be in those parts of the investment universe that are more reasonably priced, now.

As in 2000, the index has become dominated by large technology companies, this time as part of the AI boom. We are paying attention to our principles, mindful that these trends may not persist.

We pay, temporarily, in performance. Our approach has us lagging the S&P 500 recently; we’re not going up by as much, but our efforts now are made in an attempt to potentially go down by less when the bust comes. No guarantees. But we’re turning to history as a guide.

Clients, now as ever, reach out any time with your questions. We’re here to help.


Neither the past performance of the S&P, nor the described methodology, is a guarantee of future returns.

Content in this material is for general information only and not intended to provide specific advice or recommendations for any individual. All indices are unmanaged and may not be invested into directly.

All investing involves risk including loss of principal. No strategy assures success or protects against loss.


Want content like this in your inbox each week? Leave your email here.

Play the audio version of this post below:

Trends May Not Persist: What’s on the other side of the peak? 228Main.com Presents: The Best of Leibman Financial Services

The text of this episode is available at ⁠⁠⁠⁠⁠228Main.com⁠⁠⁠⁠⁠.

Friends, Waffles, and Work

In Parks & Recreation, the heroine Leslie Knope knows exactly what she’s about: waffles, friends, work. No matter what, “work is last.” The thing is, Leslie loves work and loves being of service. She helps us remember why we work—and what we want for our relationships and our legacy.


Want content like this in your inbox each week? Leave your email here.

Who Is “ABLE”?—Achieving a Better Life Experience 

In the finance industry, you will find an abundance of acronyms. From IRA to RMD and everything in between, we don’t expect you to keep track of all the acronyms, but there is one we wanted to break down with you here: the ABLE account.

What are ABLE accounts? They are tax-advantaged savings plan or investment option for individuals with disabilities who qualify.

Who is eligible?

Individuals are eligible to open an ABLE account if their disability began before age 46 and they meet the required severity of disability in one of two ways:

  1. Receiving Supplemental Security Income or Receiving Social Security Disability Insurance benefits, or
  2. Having a licensed physician sign a document including the diagnosis and notes stating they have “marked and severe” functional limitations that began before age 46.

What’s the purpose? The goal is to take advantage of tax-free growth potential and allow beneficiaries to save for qualified disability expenses, such as:

  • Housing
  • Transportation
  • Health
  • Education

Another benefit of ABLE accounts is they do not affect eligibility for benefits like SSI and Medicaid. Lots of public benefit programs restrict eligibility to people with less than $2,000 in countable resources (like cash or retirement accounts). With ABLE accounts, up to $100,000 can be excluded as a countable resource.

ABLE plans available vary by state. It’s recommended to review the plan of the state where you live first because there may be tax deductions or credits available.

How are they opened and funded? ABLE accounts can be opened and managed by the beneficiary themselves, or if the beneficiary is under 18, another individual can be appointed to manage the account. Anyone can deposit money directly into the ABLE account, including the account owner, friends, or family. (Do keep in mind that the total ABLE plan balance limit is the same as the state’s limit for 529 plans, which varies.)

For those who need it, ABLE accounts can be a great resource. We believe that everyone should have access to investing and saving opportunities, and ABLE accounts are another option to consider when appropriate.

The market doesn’t discriminate, and neither do we. Clients, if you want to talk more about what options may be available to you, reach out any time.

For more information on this topic, visit the ABLE National Resource Center, managed by the National Disability Institute.


The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.  

Investing involves risk including loss of principal. No strategy assures success or protects against loss.  

This information is not intended to be a substitute for individualized tax advice. We suggest that you discuss your specific tax situation with a qualified tax advisor


Play the audio version of this post below:

Who Is “ABLE”?—Achieving a Better Life Experience 228Main.com Presents: The Best of Leibman Financial Services

The text of this episode is available at ⁠⁠228Main.com⁠⁠.

We Are All Connected

It’s not as simple as “us” and “them.” Whether it’s politics, social issues, or economics, there are real costs when we forget the fundamental truth: we are all connected. This week Mark takes a thoughtful look at how our choices and lives are tied to one another. What’s the future we want to build, together


Want content like this in your inbox each week? Leave your email here.

You already have it within you?

You don’t need to follow a yellow brick road or consult a man behind a curtain to feel confident about your financial future. This week, Greg borrows a little inspiration from a classic story to remind us the key to a successful retirement may already be within our reach.


Want content like this in your inbox each week? Leave your email here.